A business can have strong sales, healthy cash flow, and a growing customer base while still having financial reporting issues that management does not see.
As operations become larger, financial transactions increase, more employees become involved in financial processes, and the number of accounts requiring oversight can grow quickly. Small inconsistencies that were easy to correct in a smaller business can become more difficult to identify when the organization expands.
This is where audit services can provide a more detailed review of a company’s financial records and reporting processes. GreenGrowth CPAs provides audit support that examines financial information, supporting documentation, and relevant processes to help determine whether financial statements provide a reliable representation of the business.
For growing businesses, that reliability can matter when making decisions about financing, expansion, ownership changes, investment, and long-term planning.
Why Financial Reporting Becomes More Important as a Business Grows
A growing business usually generates more financial information.
There may be additional employees, suppliers, customers, bank accounts, locations, assets, and financial transactions. Management may also introduce new systems or delegate financial responsibilities to different members of the organization.
Growth can create opportunities, but it can also make financial oversight more complicated.
A business owner who once reviewed every transaction personally may eventually depend on accounting staff, department managers, outside vendors, or automated systems. With more people and processes involved, management needs confidence that financial information is being recorded consistently and supported by appropriate documentation.
Reliable financial reporting can help answer important questions such as:
- Are revenues being recorded in the correct periods?
- Are expenses properly classified?
- Are assets and liabilities accurately reported?
- Are financial records supported by appropriate documentation?
- Are internal processes working as intended?
- Are there unusual transactions that require further review?
- Do the financial statements fairly represent the company’s financial position?
An audit can provide an independent examination of these areas.
When Should a Growing Business Consider an Audit?
Not every business needs an audit at the same stage of growth. The need can depend on the company’s structure, financing arrangements, ownership requirements, industry, and applicable reporting obligations.
However, several situations may make an audit particularly useful.
The Business Is Preparing for Financing
Lenders and investors may want reliable financial information before providing capital.
An independently examined set of financial statements can give external parties greater confidence in the information being presented.
This can be particularly important when a company is seeking a significant loan, preparing for an investment round, or evaluating other sources of capital.
The Company Is Expanding
Expansion often introduces additional financial complexity.
A company opening another location, acquiring another business, or significantly increasing its workforce may need stronger financial controls and reporting processes.
An audit can help management understand whether existing processes are keeping pace with the company’s growth.
Ownership Is Changing
A change in ownership can create a need for reliable financial information.
Whether a company is bringing in new investors, transferring ownership interests, or preparing for a potential sale, accurate financial statements can help stakeholders evaluate the business.
Financial Processes Are Becoming More Complex
As a business grows, responsibilities that were previously handled by one or two people may be divided among several employees.
For example, one person may approve purchases, another may process invoices, and another may reconcile the bank account.
Separating responsibilities can strengthen financial controls, but it also means management needs to understand whether those controls are operating effectively.
Management Wants Greater Confidence in Its Numbers
An audit does not have to be viewed only as something required by an outside party.
Management may also use an audit to obtain an independent perspective on financial reporting.
This can be useful when leadership wants to verify the reliability of financial information before making a major business decision.
What Does an Audit Examine?
The exact procedures performed during an audit depend on the company and the engagement, but auditors generally examine financial information and the evidence supporting it.
Revenue
Revenue is an important area because errors in timing, classification, or recording can affect the financial statements significantly.
Auditors may examine transactions and supporting documentation to assess whether revenue has been recorded appropriately.
Expenses
Expenses may be reviewed to determine whether they are properly recorded, classified, and supported.
This can include reviewing invoices, payment records, contracts, and other documentation.
Assets
Assets such as cash, accounts receivable, inventory, property, and equipment may require different forms of testing.
The objective is to determine whether the reported balances are supported and appropriately presented.
Liabilities
Auditors may also review accounts payable, loans, accrued expenses, and other obligations.
Incomplete or incorrectly recorded liabilities can make a company’s financial position appear stronger than it actually is.
Internal Controls
Financial reporting does not exist separately from the processes that produce it.
Auditors may consider relevant internal controls to understand how financial information is created, reviewed, approved, and recorded.
Strong controls can help reduce the risk of errors and improve the reliability of financial information.
What Is the Difference Between an Audit and a Regular Financial Review?
A business may receive financial information from its accounting team every month without undergoing an audit.
Monthly financial reporting and an audit serve different purposes.
Monthly financial reporting is generally designed to help management monitor business performance. It can show revenue, expenses, profit, cash flow, and other financial measures.
An audit provides an independent examination of financial statements and supporting evidence under applicable auditing standards.
The two can work together.
Regular financial reporting helps management monitor the business throughout the year, while an audit can provide additional assurance over the financial statements for a specific reporting period.
Identifying a Financial Reporting Issue
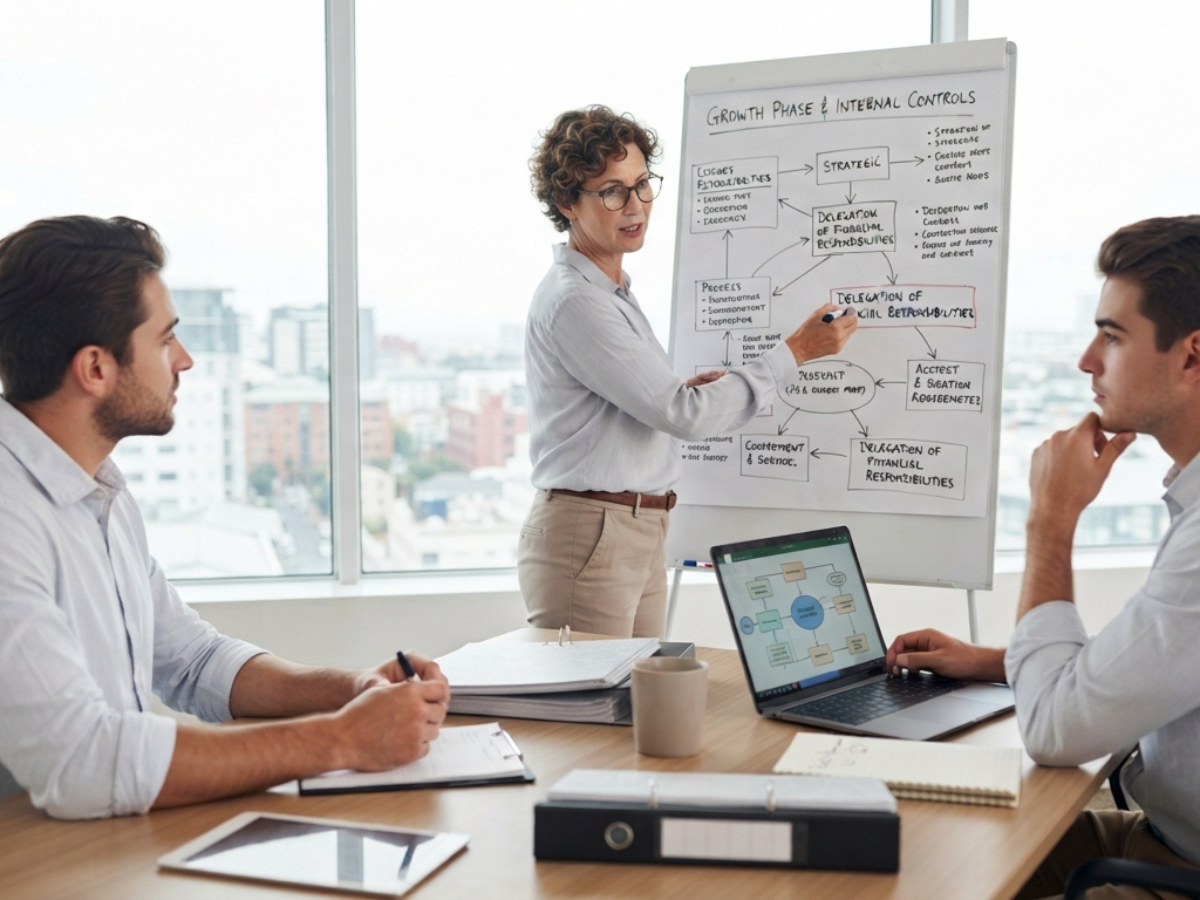
Consider a manufacturing company that had grown from $4 million to approximately $9 million in annual revenue within three years.
Management believed the company’s financial reporting was accurate because the accounting team completed monthly reconciliations and prepared regular financial statements.
During an audit, however, several transactions received additional review. The examination identified approximately $120,000 in expenses that had been recorded in the wrong reporting period, along with $75,000 in outstanding liabilities that had not been properly reflected in the financial statements.
The adjustments changed the company’s reported results for the period and gave management a clearer understanding of its actual financial position.
The issue did not necessarily mean the company’s accounting team had failed. The business had grown considerably, and processes that worked effectively when revenue was lower had not been updated to reflect the company’s increased transaction volume.
After the review, management strengthened its month-end procedures, improved documentation requirements, and established additional review steps for significant transactions.
This example illustrates how an audit can identify reporting issues as a business grows. Actual findings and financial impacts vary by company.
How Audit Findings Can Help Management
An audit should not end with the delivery of financial statements.
The findings can provide management with information about areas that may need attention.
For example, an audit may reveal:
- Inconsistent account classifications
- Weak documentation practices
- Delays in account reconciliation
- Inadequate approval procedures
- Unrecorded or incorrectly recorded liabilities
- Issues with revenue recognition
- Differences between operational and accounting records
- Opportunities to strengthen internal controls
Not every finding represents a major financial problem.
Some may involve relatively small process improvements. Others may point to issues that require immediate attention.
What matters is understanding what the findings mean and deciding how the business should respond.
Want a clearer view of your financial reporting? Schedule a consultation to discuss your audit needs, financial reporting processes, and business goals.
How Businesses Can Prepare for an Audit
Preparation can make the audit process more organized and efficient.
A business should maintain appropriate supporting documentation throughout the year rather than trying to gather everything shortly before the audit begins.
Keep Financial Records Organized
Financial statements should be supported by appropriate accounting records.
Bank reconciliations, general ledger details, invoices, contracts, payment records, and other documentation should be organized and accessible.
Reconcile Accounts Regularly
Accounts should be reconciled consistently rather than allowing differences to accumulate.
Regular reconciliations can make it easier to identify discrepancies while the underlying transactions are still easy to investigate.
Maintain Clear Documentation
Significant transactions should have appropriate supporting documentation.
This can help management and auditors understand why a transaction occurred, who approved it, and how it was recorded.
Review Unusual Transactions
Large, unusual, or nonrecurring transactions may require additional attention.
Management should understand the accounting treatment of these transactions and maintain documentation supporting the amounts reported.
Address Previous Issues
If previous financial reviews or audits identified problems, management should determine whether corrective actions were implemented.
Repeating the same issue can indicate that an underlying process has not been adequately addressed.
Preparing for an upcoming audit? Schedule a consultation to discuss your audit requirements and learn how your business can prepare for the process.
Audit and Assurance Can Support More Than Compliance
The purpose of an audit is not simply to satisfy a requirement.
For many growing businesses, reliable financial statements can support broader business objectives.
Management may use audited financial information when evaluating financing opportunities, assessing performance, preparing for an acquisition, discussing ownership changes, or planning a major investment.
External stakeholders may also place greater confidence in financial information that has undergone an independent examination.
That makes reliable reporting relevant beyond the accounting department.
Audit Services vs. Other Accounting Support
Different financial services serve different purposes, and a growing company may use several of them at different points in its development.
Service | Primary Purpose |
Bookkeeping | Records day-to-day financial transactions |
Monthly financial reporting | Helps management monitor financial performance |
Tax preparation | Prepares required tax filings |
Financial review | Provides limited assurance over financial statements |
Audit | Provides an independent examination of financial statements |
CFO support | Helps management with financial planning and strategic decisions |
The right combination depends on the company’s size, industry, reporting requirements, and business objectives.
An audit is not a replacement for good bookkeeping or regular financial reporting. Instead, it works alongside those processes.
What Happens During an Audit?
While the exact process can vary, an audit generally involves several stages.
Planning
The audit team first develops an understanding of the business, its operations, financial reporting, and areas that may require particular attention.
Reviewing Records
Relevant financial records and supporting documentation are examined based on the procedures required for the engagement.
Testing
Auditors may select transactions, balances, and other financial information for testing.
The procedures performed depend on the nature and risks of the engagement.
Evaluating Findings
Potential discrepancies or control issues are investigated and evaluated.
Management may be asked to provide additional documentation or explanations where necessary.
Reporting
At the end of the engagement, the auditor issues the appropriate report based on the results of the audit.
The report provides stakeholders with an independent conclusion regarding the financial statements under the applicable auditing standards.
When an Audit Becomes Part of Business Planning
Growing businesses often reach a point where financial information needs to support decisions beyond routine operations.
Management may be considering a new location, additional financing, a major equipment purchase, a merger, an acquisition, or a change in ownership.
In these situations, reliable financial statements can provide a stronger foundation for evaluating the decision.
The earlier management recognizes the importance of reliable reporting, the easier it can be to establish processes that support future growth.
An audit can be one part of that larger financial management process.
Frequently Asked Questions
What are audit services?
Audit services involve an independent examination of a company’s financial statements and supporting evidence to determine whether the statements are presented fairly under the applicable financial reporting framework. The audit process can include testing transactions and balances, evaluating relevant controls, reviewing documentation, and communicating significant findings to management.
When does a business need an audit?
A business may need an audit because of legal or regulatory requirements, lender or investor expectations, ownership arrangements, contractual obligations, or other reporting needs. Some companies also choose to undergo an audit voluntarily when management wants greater confidence in its financial statements or is preparing for a significant business event.
How long does a business audit take?
The length of an audit varies based on factors such as company size, transaction volume, financial complexity, recordkeeping quality, and the scope of the engagement. A smaller business with organized records may require less time than a larger organization with multiple locations, complex transactions, or extensive supporting documentation.
What should a company prepare before an audit?
Before an audit, a company should organize its financial statements, general ledger, account reconciliations, bank records, invoices, contracts, supporting documentation, and other requested information. Completing reconciliations and addressing known discrepancies before fieldwork begins can also help the audit process move more efficiently.
Can an audit identify accounting errors?
Yes. An audit may identify accounting errors, classification issues, missing liabilities, incorrect revenue recognition, documentation gaps, or other discrepancies. Auditors use procedures designed to obtain sufficient appropriate evidence to support their conclusions, although an audit is not designed to guarantee that every error or instance of fraud will be identified.
Build Confidence in Your Financial Reporting
Growth changes what a business needs from its financial reporting.
The processes that worked when a company was smaller may not provide the same level of oversight once transaction volumes increase, responsibilities become divided, and financial decisions become more significant.
An independent examination can give management and other stakeholders greater confidence in the financial statements while identifying areas where audit and assurance may help strengthen reporting processes and internal controls.
The objective is not simply to complete an audit. It is to maintain financial information that management can rely on as the business moves into its next stage.
If your company is growing, preparing for financing, expanding operations, or facing a major business decision, reviewing the reliability of your financial reporting can be an important step.
Schedule a consultation with GreenGrowth CPAs to discuss your audit requirements and determine the appropriate financial support for your business.
Get more GreenGrowth CPAs insights in Google Search and AI Mode.