By GreenGrowth CPAs Cannabis Team · Updated October 2026 · Cannabis Accounting
The best cannabis CPA firm for you is the one that can prove deep 280E and inventory costing experience, has a plan for Schedule III, and fits your license type, states, and audit needs. Rankings cannot tell you that, but the right questions can.
This guide gives you 12 questions, the red flags, and a comparison checklist. It reflects federal rules as of October 2026.
QUICK ANSWER
Choose a cannabis CPA firm by testing expertise, not reputation. Ask how the firm handles Section 280E and Section 471 cost of goods sold, how it is preparing medical clients for Schedule III, and which states it files in. If you need an audit, confirm PCAOB registration and independence. Then check POS and seed-to-sale experience, cash reporting, pricing, and references from operators like you.
Choosing a Cannabis CPA: At a Glance
- Tax depth: 280E still applies to adult-use sales, so cost of goods sold under Section 471 is where tax is won or lost.
- 2026 change: State-licensed medical marijuana has been in Schedule III since April 28, 2026. Adult-use marijuana remains in Schedule I.
- Audits: Only a PCAOB-registered firm may issue audit reports for SEC issuers, brokers, and dealers.
- Independence: A firm that audits you cannot also provide certain services, such as bookkeeping, to an SEC audit client.
- Next step: Bring the checklist below to every first call. Book a cannabis CPA consultation →
Why Choosing a Cannabis CPA Is Different
Most small businesses can pick a CPA based on price and convenience. Cannabis operators cannot. Federal law still treats adult-use marijuana as a Schedule I substance, so Section 280E denies every deduction except cost of goods sold for that activity.
That one rule changes everything about bookkeeping, inventory, and tax planning. A firm that gets it wrong can leave you with a tax bill on gross profit that you did not plan for. Your CPA choice is a risk decision, not just a cost decision.
Tax Questions: 280E, Schedule III, and State Rules
1. How do you handle 280E and Section 471 costing?
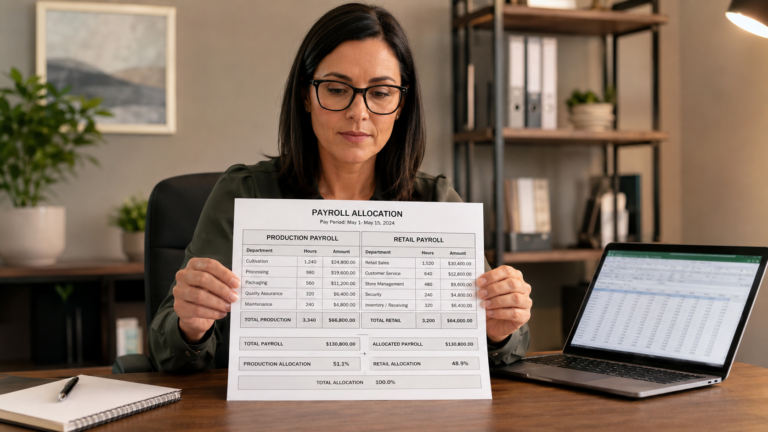
Ask the firm to walk you through which costs it puts into inventory and which it treats as nondeductible. A strong answer covers Section 471 inventory rules, cost tracking by license type, and how it documents the allocation. It should also explain how it would defend that position in an IRS exam.
2. What is your plan for Schedule III in 2026?
State-licensed medical marijuana moved to Schedule III on April 28, 2026, while adult-use stayed in Schedule I. Operators with both kinds of sales now need clean separation of revenue, costs, and expenses. Ask how the firm will split a mixed business for the 2026 return and what records it needs from you today.
3. Which states do you file in, and how do you treat decoupling?
Many states let licensed operators deduct expenses that 280E blocks federally. Oregon and New York are two examples. That means two sets of tax numbers. Ask whether the firm already files in your states and how it tracks state differences. Our cannabis tax rates by state guide shows how much the rules vary.
Audit and Independence Questions
4. Are you registered with the PCAOB?
Federal law makes it unlawful for a firm that is not registered with the PCAOB to prepare or issue an audit report for an SEC issuer, broker, or dealer. If you are public, plan to go public, or sell to a public company, this matters. A private audit for a lender does not require it.
5. Can you audit us and keep doing our books?
Often the answer should be no. SEC rules bar an auditor from providing bookkeeping, financial systems design, valuation, internal audit outsourcing, and several other services to an audit client. AICPA rules also limit nonattest work for private audit clients. Our article on auditor independence rules explains the details. Learn more about our audit and assurance services.
Systems, Cash, and Close Questions
6. Which POS and seed-to-sale systems have you worked with?
Your POS and your state tracking system hold the data behind revenue, inventory, and cost of goods sold. Ask whether the firm has reconciled your specific systems to the general ledger. Ask how it handles voids, returns, and discounts. A firm that only sees summary reports will miss the detail that supports your tax return.
7. How do you handle cash and Form 8300?
Any business that receives more than $10,000 in cash in one transaction, or in related transactions, must file Form 8300 within 15 days. It must also give the payer a written statement by January 31 of the next year. See our Form 8300 guide for the full rules.
8. What does your monthly close look like?
Ask for a target close date and a sample report package. Good reporting shows margin by category, cash, and tax set-asides.
Service, Pricing, and Track Record Questions
9. Who will actually do our work?
The partner on the sales call may not book your entries. Ask who prepares, who reviews, and how fast they respond.
10. How do you price your services?
Firms use hourly billing, fixed project fees, or a fixed monthly fee. Price depends on entity count, states, transaction volume, and the state of your records. Get the scope in writing, including what counts as out of scope.
11. Have you represented cannabis clients before the IRS?
Cannabis businesses face 280E exams and notices. Ask whether the firm has handled them and who would represent you.
12. Can we speak with clients like us?
A dispensary, a cultivator, and a vertically integrated operator have different problems. Ask for references with your license type and a similar size.
Red Flags When Hiring a Cannabis CPA
- Promises to make 280E disappear: Adult-use sales are still subject to 280E. Aggressive cost of goods sold claims can backfire in an exam.
- No answer on Schedule III: A firm with no plan for splitting medical and adult-use activity is behind.
- Audit plus bookkeeping with no independence discussion: This can disqualify the audit.
- Vague scope: A fee without a written scope often leads to surprise bills.
- No POS experience: Year-end inventory fixes are a sign the monthly work is weak.
Questions to Ask in the First Call
These five questions reveal most of what you need:
- Walk me through how you would calculate our cost of goods sold.
- What do you need from us to split medical and adult-use activity for 2026?
- Which of our states decouple from 280E, and how will you file there?
- If we need an audit later, what would change about your role?
- What does a typical month look like, and who is my main contact?
Cannabis CPA Comparison Checklist
Score each firm after the call with a short note per row.
▶ Cannabis CPA Firm Checklist
| Criterion | What a good answer looks like | Your notes |
|---|---|---|
| 280E and Section 471 | Explains what goes into COGS and how it would defend that in an exam | |
| Schedule III plan | Separates medical and adult-use activity and has a 2026 return plan | |
| States and decoupling | Files in your states and tracks which ones decouple from 280E | |
| Audit capability | PCAOB registered if you are, or may become, an SEC filer | |
| Independence | Explains which services it can and cannot provide if it audits you | |
| POS and seed-to-sale | Has reconciled your POS and tracking system to the books before | |
| Cash and Form 8300 | Has a process to catch cash over $10,000 and file within 15 days | |
| Close and reporting | Gives a monthly close date and a standard report package | |
| Team and access | Names who does the work and how fast they respond | |
| Pricing | Puts scope, fee model, and extras in writing | |
| IRS exam support | Has represented cannabis clients in exams or notices | |
| References | Offers clients with your license type and size |
Where GreenGrowth CPAs Fits
GreenGrowth CPAs is a PCAOB-registered firm and an AICPA member based in Irvine, CA. We were founded in 2016 and have served more than 1,500 clients. Our cannabis accounting team works with cultivators, manufacturers, and retailers, including dispensary accounting clients.
We are one option, not the only one. Run us through the same 12 questions you use for any firm, and choose the one whose answers fit your business best.
KEY TAKEAWAYS
- ›The best cannabis CPA firm is the one that fits your license type, states, and stage, not the one at the top of a list.
- ›Test 280E and Section 471 depth first. That is where most cannabis tax risk sits.
- ›Medical sales moved to Schedule III on April 28, 2026. Your firm should have a plan for mixed operations.
Frequently Asked Questions
There is no single best cannabis CPA firm for every business. The best cannabis CPA firm for you is the one that matches your license type, your states, and your stage. Look for proven 280E and Section 471 experience, a clear plan for Schedule III, and real familiarity with your seed-to-sale and POS systems. If you need an audit for investors or the SEC, confirm PCAOB registration and independence. Ask for references from operators like you.
Cost depends on scope more than on the firm's name. The main drivers are the number of entities and licenses, how many states you file in, whether you need monthly bookkeeping or only tax returns, transaction volume, and how clean your records are. Audits and IRS exams add cost. Firms charge by the hour, by the project, or with a fixed monthly fee. Ask for a written scope and a quote that lists what is included and what is extra.
In most cases, yes. A licensed cannabis business follows tax rules that general practitioners rarely see. Section 280E still blocks deductions for adult-use sales, and inventory costing under Section 471 drives your federal tax bill. Medical operators also need help with the 2026 move to Schedule III. A general CPA can learn these rules, but you pay for that learning curve. Mistakes in cost of goods sold can lead to large IRS adjustments years later.
Start with their 280E and Section 471 approach and how they defend cost of goods sold in an IRS exam. Ask how they handle Schedule III for medical sales, which states they file in, and how they treat state decoupling. Confirm their POS and seed-to-sale experience. If you need an audit, ask about PCAOB registration and independence. Finally, ask who does the work, how often you will meet, and how they price.
Sometimes, but independence rules limit it. For SEC registrants, the SEC bars an auditor from providing services such as bookkeeping, financial systems design, valuation, and internal audit outsourcing to an audit client. AICPA rules also restrict nonattest services for private audit clients and require management to own the books. Many operators use one firm for audit and another for accounting and tax. Ask any firm how it will protect independence before you sign.
A good one should. Any business that receives more than $10,000 in cash in one transaction, or in related transactions, must file Form 8300 within 15 days. It must also send the payer a written statement by January 31 of the next year. Cash-heavy cannabis businesses often face this when vendors, landlords, or wholesale buyers pay in cash. Your CPA should help you set up a tracking process and file on time.
Interview Us With the Same 12 Questions
Book a free consultation with our cannabis team. Bring your checklist, and we will answer every question in writing.
KEY NUMBERS
Pick a Cannabis CPA With Proof, Not Promises.
Talk with our cannabis team about 280E, Schedule III, audits, and your states.
Book Your Free Consultation →GreenGrowth CPAs · Cannabis Team
Get more GreenGrowth CPAs insights in Google Search and AI Mode.