By GreenGrowth CPAs Cannabis Team · Updated October 2026 · Cannabis Tax
The Oregon cannabis tax is a 17% state tax on the retail price of recreational marijuana, plus up to 3% more in cities and counties whose voters approved a local tax. That puts the most a shopper can pay at 20%, and registered medical patients pay none of it.
For operators, the retail tax is only half the picture. Oregon also lets licensed businesses deduct the expenses that federal Section 280E disallows. This guide covers both, as of October 2026.
QUICK ANSWER
Oregon taxes recreational cannabis at 17% of the retail sales price. Cities and counties can add up to 3% with voter approval, for a maximum of 20%. Retailers collect the tax and file quarterly returns with the Oregon Department of Revenue. Registered medical patients and their caregivers are exempt. For income tax, Oregon disregards federal Section 280E, so licensed businesses deduct normal expenses on their state return.
Oregon Cannabis Tax: At a Glance
- State rate: 17% of the retail sales price on every recreational marijuana item, from flower to edibles.
- Local option: Up to 3% more where voters approved a city or county tax.
- Filing: Retailers file quarterly by January 31, April 30, July 31 and October 31.
- State 280E treatment: Oregon allows the deductions that 280E blocks federally, for both individuals and corporations.
- How we help: GreenGrowth CPAs prepares federal and Oregon returns for cannabis operators and builds the books that support both. Book a cannabis tax review →
Oregon Cannabis Tax Rate Overview
Oregon voters legalized adult-use marijuana with Measure 91 in 2014. Unlike many states, Oregon puts no excise tax on growers or wholesalers. The whole state cannabis tax falls on the consumer at the register.
Oregon also has no general sales tax, so the marijuana tax is the only consumption tax a buyer sees. For a side-by-side view of every legal state, see our full guide to cannabis tax rates by state.
State Cannabis Sales Tax (17%)
What the 17% Covers
ORS 475C.674 imposes the tax at 17% of the retail sales price. It covers usable marijuana, immature plants, edibles, concentrates, extracts, topicals and other cannabinoid products. The rate is the same for every product, with no potency tiers.
The statute calls it a direct tax on the consumer, and the retailer collects it. In practice, the retailer answers for any tax it fails to collect or remit.
The Medical Exemption
ORS 475C.678 exempts sales to registry identification cardholders under the Oregon Medical Marijuana Program. It also exempts a designated primary caregiver buying for a cardholder. The buyer must show proof at the time of sale. Keep a record of every card check.
Local Option Cannabis Tax (up to 3%)
ORS 475C.453 lets a city or county adopt a local marijuana tax. The cap is 3%, and the governing body must refer the ordinance to voters at a statewide general election. Portland and Eugene are two cities that levy one. A shopper in a city with the full local tax pays 20% in total.
Localities can sign an agreement for the Oregon Department of Revenue to collect the tax for them. Those without one collect on their own, so check the rules for every store location. The department lists participating cities and counties on its marijuana locality tax page.
Oregon vs Other State Cannabis Tax Rates
Oregon sits at the low end once you add up every layer. The table shows state-level cannabis taxes as of October 2026.
▶ Adult-Use Cannabis Taxes by State (October 2026)
| State | Main cannabis tax | Other layers |
|---|---|---|
| Oregon | 17% state retail tax plus up to 3% local | No general sales tax; registered medical patients exempt |
| Washington | 37% excise on the retail sales price | State and local retail sales tax also apply |
| California | 15% excise on gross receipts (Oct. 1, 2025 through June 30, 2028) | State and local sales tax also apply to adult-use sales |
| Colorado | 15% retail marijuana sales tax | Plus a 15% excise tax on the first wholesale transfer |
| Michigan | 10% adult-use excise plus 6% sales tax | Plus a 24% wholesale tax in effect since January 1, 2026 |
| Illinois | 10%, 20% or 25% purchaser excise, by product and THC level | Plus 7% cultivation privilege tax and state and local sales tax |
Washington's 37% rate is more than double Oregon's 17%. Michigan's new 24% wholesale tax is the biggest change on the list this year.
OLCC Compliance and Tax Collection
Who Files and When
The Oregon Liquor and Cannabis Commission licenses producers, processors, wholesalers, retailers and labs. The Department of Revenue runs the tax. Under ORS 475C.682, each retailer collects the tax at the point of sale and files a return every quarter.
- January to March: due April 30
- April to June: due July 31
- July to September: due October 31
- October to December: due January 31
Payment is due with the return. Retailers file through Revenue Online or with Form OR-MTR, and can pay electronically or by cash, check or money order with a voucher.
Where Retailers Slip
Most problems start with point-of-sale settings, such as a wrong local rate or a skipped medical card check. Reconcile POS tax reports to your Cannabis Tracking System sales and bank deposits each month. Our dispensary accounting team runs that reconciliation for Oregon stores.
💬 The Conversation Worth Having
Oregon taxes a very different profit than the IRS does. If your preparer copies federal taxable income onto the Oregon return, you may pay state tax on expenses Oregon lets you deduct. Ask to see the 280E subtraction on your last Oregon return.
Running an Oregon dispensary? Let's check your retail tax filings and your state 280E subtraction.
Book a Review →280E Federal Treatment for Oregon Operators
Section 280E of the Internal Revenue Code bars deductions for a business that traffics in Schedule I or II controlled substances. A retailer can deduct cost of goods sold, but not rent, budtender payroll, marketing or most overhead.
That changed in part in 2026. State-licensed medical marijuana moved to Schedule III effective April 28, 2026, so 280E no longer reaches those medical sales. Adult-use marijuana stays in Schedule I. So every adult-use sale in Oregon still falls under 280E on the federal return. Our breakdown of the 2026 rescheduling order and 280E explains what changed and what did not.
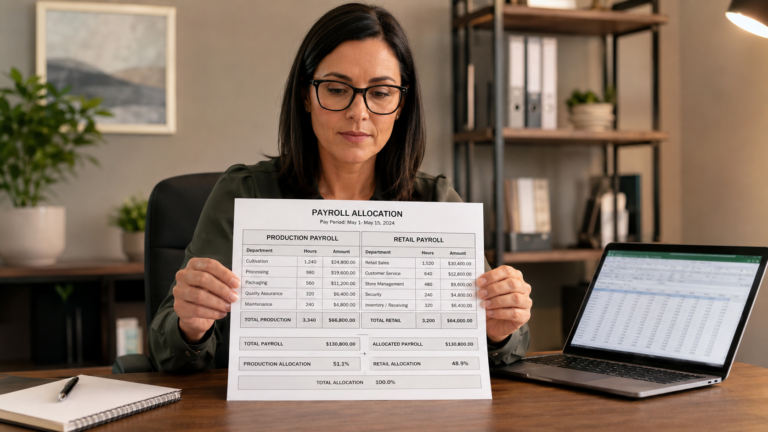
Businesses with both medical and adult-use revenue need a defensible way to split costs. See our guide to 280E expense allocation for the methods.
Oregon State 280E Decoupling Status
Oregon is fully decoupled from 280E for state-legal cannabis businesses, and that remains true in 2026. Two statutes do the work.
- Personal income tax: ORS 316.680(1)(i) lets owners subtract any federal deduction they would have taken for producing, processing or selling marijuana but for 280E. This covers sole proprietors and owners of pass-through entities.
- Corporate excise tax: ORS 317.363 says 280E applies to controlled substance trafficking except conduct authorized under Oregon's marijuana laws. A C corporation computes Oregon income as if 280E did not exist.
The subtraction only helps if your books track the disallowed expenses. Oregon's corporate rate is 6.6% on the first $1 million of taxable income and 7.6% above that. Individual rates run from 4.75% to 9.9%.
Tax Planning Opportunities for OR Dispensaries
Capture the Full State Subtraction
Build a federal 280E workpaper that lists each disallowed expense by account. Carry the total to the Oregon subtraction line every year. Review prior returns too. If a past Oregon return missed the subtraction, an amended return may recover tax while the statute of limitations is still open.
Maximize Cost of Goods Sold
Federal 280E still allows cost of goods sold. Vertically integrated operators should capture production and processing costs in inventory. Retailers have less room, but freight-in belongs there too.
Separate Medical Activity
Track sales to OMMP cardholders on their own. Exempt sales need card records, and medical revenue may fall outside 280E after rescheduling.
Plan Quarterly, Not Annually
A quarterly review catches POS rate errors early and keeps cash set aside for retail and income tax. Our tax planning and compliance team builds that calendar for cannabis businesses in Oregon and other states.
Frequently Asked Questions
Oregon charges a 17% state tax on the retail sales price of recreational marijuana items. Cities and counties may add a local tax of up to 3% if their voters approve it, so the combined rate tops out at 20%. Oregon has no general sales tax, so nothing else is stacked on the receipt. Registered medical patients and their designated primary caregivers are exempt from the retail marijuana tax when they show proof of registration at the counter.
Oregon taxes cannabis at the point of sale. The consumer pays a 17% state tax plus any approved local tax of up to 3%, and the OLCC-licensed retailer collects it at the register. Retailers then file quarterly returns and remit the money to the Oregon Department of Revenue. Growers, processors, and wholesalers do not pay a separate state excise tax. Business profits are also subject to Oregon income or corporate excise tax, where state law disregards federal Section 280E.
The Oregon Department of Revenue administers the state marijuana retail tax. It processes the quarterly returns, takes payments, and handles audits and collections. Many cities and counties also sign agreements that let the department collect their local marijuana tax for them. The Oregon Liquor and Cannabis Commission licenses and regulates the businesses, but it does not process the tax returns. Income and corporate excise taxes on cannabis profits are also handled by the Department of Revenue.
Yes. Oregon disconnected its tax code from Section 280E for state-licensed cannabis businesses. ORS 316.680 lets personal income taxpayers subtract the deductions that 280E denied on the federal return. ORS 317.363 says 280E does not apply to conduct authorized under Oregon's marijuana laws for corporate excise purposes. The result is that Oregon taxes your real net profit. Federal law still applies 280E to adult-use sales, so you keep two sets of tax books.
On a recreational purchase, expect 17% state tax plus up to 3% local tax, or as much as 20% in total. For example, a $50 purchase in a city with the full local tax would carry $8.50 of state tax and $1.50 of local tax, for $60 at checkout. In a city or county without a local tax, the same purchase costs $58.50. Registered medical cardholders pay no retail marijuana tax at all.
The OLCC is the Oregon Liquor and Cannabis Commission. It regulates the sale of alcohol and the production, processing, and sale of recreational marijuana. For cannabis, it licenses producers, processors, wholesalers, retailers, and labs, and it enforces rules on packaging, labeling, testing, and inventory tracking. The Oregon Health Authority runs the separate medical marijuana program. The OLCC does not collect cannabis tax, but tax compliance problems can still affect a license.
Where to Go From Here
Pay the Right Oregon Tax, Not the Federal One
We review your quarterly filings and local rates and confirm your Oregon return claims the full 280E subtraction.
KEY NUMBERS
Oregon Gives Back What 280E Takes. Make Sure You Claim It.
Talk with our cannabis team about your federal and Oregon filings.
Book Your Free Consultation →GreenGrowth CPAs · Cannabis Team
Get more GreenGrowth CPAs insights in Google Search and AI Mode.