By GreenGrowth CPAs Cannabis Team · Updated October 2026 · Cannabis Tax
IRC 280E denies every federal deduction and credit to a business that traffics in a Schedule I or II controlled substance, and adult-use cannabis is still Schedule I. Your only federal offset is cost of goods sold, so how you calculate and track COGS under Section 471 largely sets your federal tax bill.
The ground shifted in 2026. State-licensed medical marijuana moved to Schedule III on April 28, 2026, so 280E no longer reaches that activity going forward. Adult-use sales stay under 280E.
QUICK ANSWER
IRC 280E disallows all deductions and credits for a business trafficking in Schedule I or II drugs. Cannabis operators can still subtract properly calculated cost of goods sold. Resellers include only product cost plus freight and acquisition charges. Producers can also capitalize direct labor and production overhead. Medical marijuana under a state license moved to Schedule III effective April 28, 2026, while adult-use cannabis remains under 280E.
IRC 280E: At a Glance
- The rule: No deduction or credit for a business trafficking in Schedule I or II controlled substances.
- The exception: COGS is not a deduction, so it still reduces gross receipts.
- Resellers vs. producers: Resellers capitalize product and acquisition costs; producers add labor and production overhead.
- Section 263A: Not available to 280E taxpayers, per Harborside (Tax Court 2018, Ninth Circuit 2021).
- 2026 change: State-licensed medical marijuana is Schedule III as of April 28, 2026; adult-use remains Schedule I.
What Does IRC 280E Say?
Section 280E is one sentence long. It denies any deduction or credit for amounts paid or incurred in a trade or business that consists of trafficking in Schedule I or II controlled substances. The rule applies when federal law or the law of the state prohibits that trafficking.
Federal law still prohibits marijuana, so a state license does not change the federal answer. The IRS says this directly in its cannabis guidance. Rent, payroll, marketing, security, and professional fees all become nondeductible, and credits are lost too.
Why COGS Is the Only Federal Relief
Section 280E blocks deductions and credits. Cost of goods sold is neither. It is a reduction of gross receipts in arriving at gross income, which comes before any deduction. The IRS confirms that 280E does not stop a cannabis business from reducing gross receipts by properly calculated COGS.
That makes inventory costing the main lever you control. A cost that belongs in inventory under the Section 471 regulations reduces taxable income; a cost booked as operating expense is lost. Our guide to cannabis COGS cost tracking and allocation walks through the bookkeeping side in more detail.
Section 471 for Resellers vs. Producers: What Goes Into COGS
The regulations treat resellers, such as dispensaries buying packaged product, differently from producers, such as cultivators and manufacturers. Vertically integrated operators need separate cost pools for each.
▶ What You Can Capitalize Into Inventory
| Cost | Reseller (1.471-3(b)) | Producer (1.471-3(c), 1.471-11) |
|---|---|---|
| Product or raw materials | Yes: invoice price less trade discounts | Yes: seeds, clones, nutrients, growing media, inputs |
| Freight and acquisition charges | Yes: transportation and other necessary charges to take possession | Yes |
| Direct labor | No | Yes: cultivation, trimming, extraction, packaging labor |
| Production overhead | No | Yes: grow room rent and utilities, repairs, indirect labor, supervision, quality control |
| Selling and marketing | No | No: excluded by 1.471-11(c)(2)(ii) |
| General and administrative | No | No: excluded by 1.471-11(c)(2)(ii) |
| Retail rent, budtenders, store security | No | No |
A dispensary has a narrow COGS base, so its wins come from capturing all freight-in, applying vendor discounts correctly, and costing shrink consistently. A producer has far more room when it tracks costs by facility and function. See our dispensary accounting services.
Why Section 263A Is Off the Table
Section 263A, the uniform capitalization rules, normally pulls more overhead into inventory. Some dispensaries used it to move store costs into COGS until Harborside ended that approach.
In Patients Mutual Assistance Collective Corp. v. Commissioner, 151 T.C. 176 (2018), the Tax Court held that a dispensary subject to 280E must compute COGS under the Section 471 regulations for resellers. Under the flush language of Section 263A(a)(2), a cost that could not otherwise reduce taxable income cannot be capitalized. Because 280E disallows those costs, 263A cannot revive them. On April 22, 2021, the Ninth Circuit affirmed.
Separate Trade or Business (CHAMP) and Its Limits
Taxpayers have one real win on scope: Californians Helping to Alleviate Medical Problems, Inc. v. Commissioner, 128 T.C. 173 (2007), or CHAMP. The Tax Court found that CHAMP ran a genuine caregiving business separate from its marijuana activity, so those caregiving expenses stayed deductible.
Later cases show how narrow that door is. In Olive v. Commissioner, the Ninth Circuit held that free services offered alongside marijuana sales were not a separate trade or business. A separate business needs its own revenue, economic substance, and books; branded apparel at the register will not qualify. Licensing intellectual property through a separate entity is one structure some operators review, and we cover its risks in using IP royalties to manage 280E.
What 280E Does to Your Effective Tax Rate: A Hypothetical
The example below is hypothetical and simplified. It assumes a C corporation dispensary paying only the 21% federal corporate rate, with no state tax and no medical sales.
▶ Hypothetical Dispensary: Federal Tax With and Without 280E
| Line item | Without 280E | With 280E | With 280E, better COGS capture |
|---|---|---|---|
| Revenue | $5,000,000 | $5,000,000 | $5,000,000 |
| Cost of goods sold | $2,500,000 | $2,500,000 | $2,650,000 |
| Operating expenses | $1,800,000 | $1,800,000 | $1,650,000 |
| Book income before tax | $700,000 | $700,000 | $700,000 |
| Federal taxable income | $700,000 | $2,500,000 | $2,350,000 |
| Federal tax at 21% | $147,000 | $525,000 | $493,500 |
| Tax as a share of book income | 21% | 75% | 70.5% |
Hypothetical illustration only. The third column assumes $150,000 of freight-in and acquisition charges were moved from operating expense to inventory under Treas. Reg. 1.471-3(b). Actual results depend on your facts.
Under 280E, the tax follows gross profit, not book profit. Each dollar correctly moved into COGS saves 21 cents of federal tax in this example. See our cannabis tax rates by state for the excise and sales tax layer on top.
Not sure your COGS captures every allowable cost? We will review your inventory costing against the Section 471 rules.
Book a COGS Review →How to Track Cannabis COGS in Real Time
Real-time COGS tracking means your general ledger knows the cost of every unit you sell when you sell it. You build that by tying your seed-to-sale system, your point of sale, and your accounting system together, then closing inventory every month.
Integrate Seed-to-Sale and POS With the Ledger
Your state tracking system, such as Metrc in many states, records every package and transfer. Your POS records every sale. Map both to inventory items in your accounting system so each sale relieves inventory at cost. A POS that pushes only revenue totals leaves cost data trapped until year end.
Use Standard Costs and Review Variances
Set a standard cost for each SKU or batch, including freight for resellers and labor and overhead for producers. Compare actual costs to standard monthly. Large variances usually point to missed freight, wrong counts, or unrecorded waste.
Close Inventory Monthly
- Count high-value SKUs weekly and the full store or facility at least monthly.
- Reconcile the physical count to seed-to-sale and to the ledger balance.
- Record shrink, samples, and destroyed product with documentation.
- Allocate production overhead to batches using a written, consistent method.
IRC 280E After the 2026 Schedule III Order
Acting Attorney General Todd Blanche signed the final order on April 22, 2026. It appeared in the Federal Register as document 2026-08176 and took effect April 28, 2026. The order places FDA-approved marijuana drug products and marijuana held under a state medical marijuana license in Schedule III. It also creates expedited DEA registration for state medical licensees. Adult-use marijuana remains Schedule I, so 280E still applies to adult-use sales.
Treasury and the IRS announced on April 23, 2026, that they plan to issue guidance. They said rescheduling generally removes 280E as a bar for businesses that no longer traffic in Schedule I or II substances. The forthcoming guidance is expected to include a transition rule that applies relief for the full taxable year that includes the effective date. For a calendar-year medical operator, that points to all of 2026. The announcement does not say whether DEA registration is a condition.
Broader rescheduling is still unsettled. A DEA administrative hearing on rescheduling marijuana generally ran from June 29 to July 15, 2026. On September 29, 2026, the presiding judge paused the proceeding while deciding whether to admit a new GAO report into the record. Separate petitions challenging the April order are pending in the D.C. Circuit. Our Schedule III rescheduling guide for dispensaries tracks these developments.
Dual Licenses: Allocating Medical and Adult-Use Costs
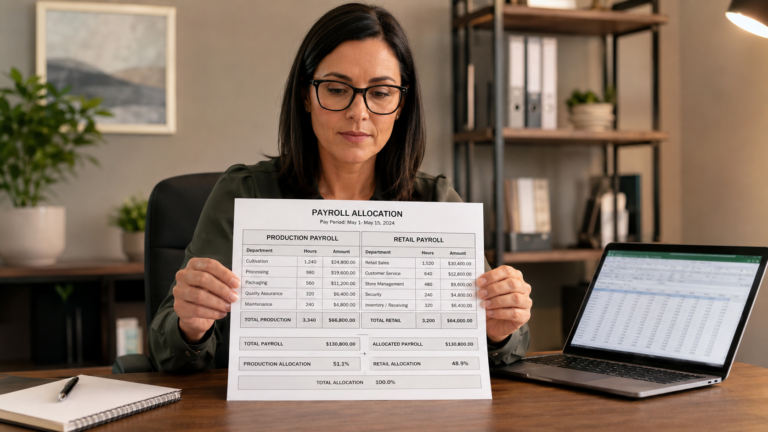
Operators with both medical and adult-use activity now sit on both sides of the line. Treasury expects its guidance to explain how 280E reaches only the Schedule I or II activity, for example by apportioning expenses. Until then, build a defensible method:
- Track medical and adult-use revenue separately in the POS from April 28, 2026, forward.
- Assign direct costs, such as medical-only staff, to the activity that caused them.
- Allocate shared costs, such as rent and security, by revenue, square footage, or labor hours, and document the method.
Expect the IRS to test your allocation. Our article on 280E expense allocation between medical and adult-use costs covers drivers and documentation in more depth.
States That Decouple From 280E
Many states let licensed cannabis businesses deduct, on the state return, expenses that 280E disallows. The table lists only states we confirmed on state government sources. Rules differ by license and tax type.
▶ State 280E Decoupling, Verified as of October 2026
| State | What the state allows | Key limits |
|---|---|---|
| California | R&TC 17209 lets licensees under the personal income tax law deduct business expenses | Personal income tax law only; SB 167 extends it to tax years beginning before Jan. 1, 2030 |
| Colorado | Subtraction for 280E-disallowed expenses of licensed marijuana businesses | Tax years 2014 and later; pro forma federal schedules required |
| Connecticut | Deduction for personal income and corporation business taxpayers | Medical and adult-use licensees; 2023 tax year forward |
| Illinois | Subtraction for 280E-disallowed deductions of cannabis establishments | Added by Public Act 103-0008, first on 2023 returns |
| Maryland | Subtraction for licensed growers, processors, dispensaries, and other establishments | Tax years beginning after Dec. 31, 2021 |
| Massachusetts | Deduction for licensed marijuana establishments and medical marijuana businesses | Tax years beginning on or after Jan. 1, 2022 |
| Michigan | Deduction for adult-use establishments licensed under the MRTMA | Not available to medical facilities licensed under the MMFLA |
| Minnesota | Cannabis income tax subtraction | Medical manufacturers since 2019; licensed cannabis and hemp businesses from 2023 |
| New Jersey | Income computed as if 280E does not apply | Tax years beginning on or after Jan. 1, 2023; rider required |
| New York | Tax Law 612(c)(46) subtraction for 280E-disallowed amounts | Adult-use cannabis products |
| Oregon | Subtraction for 280E-disallowed marijuana business expenses | Licensed Oregon marijuana businesses |
| Pennsylvania | Act 56 of 2024 deduction of ordinary and necessary expenses | Medical cannabis businesses; Revenue describes it for grower/processor permit holders |
Note the Michigan twist. After April 28, 2026, a medical provisioning center may get federal relief but no Michigan deduction, while an adult-use store gets the reverse.
Amended Returns and Refund Claims: Proceed With Caution
The IRS said in June 2024 that amended-return claims arguing 280E does not apply are not valid. Treasury's 2026 transition rule points to the taxable year that includes April 28, 2026. It does not reopen earlier years.
A weak refund claim can bring penalties and an exam of other years. Weigh the theory, the limitations period, and your audit exposure first. Our post on whether to file an amended 280E refund claim explains the risk in plain terms.
280E Audit Defense: What to Have Ready
Cannabis exams focus on gross receipts and COGS. Keep these records ready for every open year:
- Monthly inventory counts reconciled to seed-to-sale and the ledger.
- Vendor invoices and freight bills supporting every dollar in COGS.
- Cash logs, bank deposits, and Form 8300 filings that tie to POS revenue.
- Your medical and adult-use allocation workpapers for 2026 forward.
For a fuller checklist, read 280E audit defense: what you would hand an examiner. Our cannabis CPA and tax team can also prepare these files before an exam starts.
Frequently Asked Questions
280E and COGS Basics
IRC 280E is a federal tax rule that denies all deductions and credits to a business that traffics in a Schedule I or II controlled substance. Because adult-use marijuana is still Schedule I, a state-licensed dispensary cannot deduct rent, payroll, marketing, or most other operating costs on its federal return. It can still subtract cost of goods sold from gross receipts. Federal tax is often based on gross profit, not net profit.
Yes. Cost of goods sold is not a deduction. It reduces gross receipts to arrive at gross income, so 280E does not block it. The IRS has confirmed that cannabis businesses may reduce gross receipts by properly calculated COGS. The key word is properly. Resellers follow Treas. Reg. 1.471-3(b), and producers follow 1.471-3(c) and the full absorption rules in 1.471-11. Costs that the regulations treat as selling or administrative expenses stay out of COGS and remain nondeductible.
A dispensary that buys finished product is a reseller under Treas. Reg. 1.471-3(b). It can include the invoice price of the cannabis, less trade and other discounts, plus transportation and other necessary charges to acquire possession. It cannot include retail rent, budtender wages, store security, marketing, or general overhead. After Harborside, a dispensary also cannot use Section 263A to capitalize those costs. Vertically integrated operators can capitalize more on the production side, such as cultivation labor and grow-room overhead.
Schedule III, Tracking, and Filing
It depends on the activity. The final order effective April 28, 2026, moved state-licensed medical marijuana and FDA-approved marijuana products to Schedule III, so 280E no longer applies to that activity going forward. Adult-use marijuana remains Schedule I, so 280E still applies to adult-use sales. Treasury has said forthcoming guidance should apply relief for the full taxable year that includes the effective date. Dual-license operators will need to apportion expenses between medical and adult-use activity.
Connect your seed-to-sale system and POS to your accounting system so each sale relieves inventory at cost. Set standard costs for each SKU or batch, including freight for resellers and labor and overhead for producers. Compare actual costs to standard every month and investigate variances. Count high-value items weekly and everything at least monthly, then reconcile counts to seed-to-sale and the ledger. Document shrink and destruction.
Be careful. In June 2024 the IRS said that refund claims arguing 280E does not apply to marijuana businesses are not valid and that taxpayers filing them are not entitled to refunds. The 2026 Treasury transition rule points to the taxable year that includes April 28, 2026, not earlier years. A weak claim can invite penalties and an exam of other years. Review the legal theory, the limitations period, and your audit exposure with a cannabis tax advisor first.
Where to Go From Here
Get Your COGS and 280E Position Right Before You File
GreenGrowth CPAs is PCAOB registered and an AICPA member, and has served 1,500+ clients since 2016. Our cannabis team reviews inventory costing, medical and adult-use allocations, and state returns for operators in licensed markets.
KEY FACTS
Every Dollar That Belongs in COGS Is a Dollar 280E Cannot Touch.
Book a free review. We will test your inventory costing, your Schedule III allocation, and your state decoupling position before your next return.
Book Your Free Consultation →GreenGrowth CPAs · Cannabis Team
Get more GreenGrowth CPAs insights in Google Search and AI Mode.